In virtually every corporate strategic planning retreat, quarterly Board of Directors meeting, or M&A investment committee session, the exact same slide is inevitably projected: the canonical four quadrants of the BCG Growth-Share Matrix—Stars, Cash Cows, Question Marks, and Dogs.
Yet in more than 80% of corporate enterprises, this strategic framework falls prey to a systemic executive failure known in Tier-1 management consulting as the “Static Sketch Syndrome”:
- The Fatal Confusion Between Absolute and Relative Market Share ($\text{RMS}$): An executive committee complacently designates a business unit as a “market leader” simply because it commands a 28% market share. However, if the primary market incumbent commands 56%, the firm’s relative share is merely $0.50\times$. In the real economics of scale, an $\text{RMS}$ of $0.50\times$ means the competitor has accumulated double the production experience, operating with structural unit cost advantages driven by the Experience Curve. The firm’s business unit is not a leader; it is an endangered sub-scale competitor.
- Total Disconnect from Free Cash Flow ($\text{FCF}$) and the Balance Sheet: Bruce Henderson’s original framework, published in 1968 for the Boston Consulting Group, was never conceived as a marketing taxonomy or branding matrix; it was engineered as a mathematical corporate liquidity allocation model. Evaluating business units without calculating their net free cash flow ($\text{FCF}$) or auditing their working capital and expansion CAPEX requirements reduces strategic planning to decorative rhetoric.
- The Sunk-Cost Trap of “Viable Dogs”: Corporate management routinely tolerates the indefinite survival of sub-scale Dogs simply because they produce a modest positive accounting profit or EBITDA margin (e.g. 4% on sales). Executive leadership overlooks the capital opportunity cost: the Return on Invested Capital ($\text{ROIC}$) of that unit is significantly lower than the company’s Weighted Average Cost of Capital ($\text{WACC}$), meaning that every dollar retained in that line destroys shareholder value.
To elevate the BCG matrix into an actionable, boardroom-grade decision engine, corporate strategy must formalize the analysis into an objective Cartesian model of Relative Market Share ($\text{RMS}$) vs. Market Growth Rate ($\text{MGR}$), simulate Bruce Henderson’s corporate cash flow balance, project an executive bubble chart scaled by revenue, and deliver a Minto Pyramid-structured capital reallocation plan.
Firm revenue, leading competitor sales, and verified market growth rates"] B["2. Cartesian Mathematical Engine: Vectors (RMS, MGR)
Strict calculation: RMS = Vi / Vleader and objective quadrant assignment"] C["3. Henderson Cash Dynamics: Net FCF Balance
Cash Cow surplus extraction and Question Mark deficit quantification"] D["4. Capital Allocation Filter: Selective Concentration
Binary decision on Question Marks, defense of Stars, and divestment of Dogs"] E["5. Executive Last Mile: Board Decision Gateway (Minto)
16:9 widescreen deck, Q1-Q4 roadmap, and formal binding resolutions"] A --> B B --> C C --> D D --> E style A fill:#F8FAFC,stroke:#94A3B8,stroke-width:1.5px,color:#0F172A style B fill:#EFF6FF,stroke:#3B82F6,stroke-width:1.5px,color:#1E3A8A style C fill:#F0FDFA,stroke:#0D9488,stroke-width:1.5px,color:#0F766E style D fill:#FFFBEB,stroke:#F59E0B,stroke-width:1.5px,color:#92400E style E fill:#0F172A,stroke:#D97706,stroke-width:2px,color:#FFFFFF
🔍 Haz clic en el diagrama para ampliarlo a pantalla completa
Executive Decision Pack: Dynamic BCG Portfolio Matrix & Capital Allocation
1. What is the BCG Matrix? Fundamentals, Portfolio Dynamics & Core Objectives
For Chief Executive Officers (CEOs), Chief Financial Officers (CFOs), private equity investment directors, and corporate strategists tasked with steering multi-business enterprises—or anyone approaching this framework for the first time—the BCG Growth-Share Matrix (originally developed by Bruce D. Henderson in 1968 and formalized in his landmark 1970 essays for the Boston Consulting Group) represents the foundational discipline for corporate portfolio management and executive capital allocation.
Unlike diagnostic frameworks focused narrowly on single product lines or functional operational efficiencies, the BCG Matrix is rooted in an indisputable corporate finance reality: in a diversified enterprise, not all business units share the same lifecycle stage, nor should they be governed by identical financial hurdles. Applying uniform dividend payout expectations or identical return targets to an emerging unit in a nascent, capital-hungry market as one does to a mature cash generator inevitably chokes off enterprise innovation; conversely, permitting mature businesses to reinvest their discretionary cash flows into low-growth sectors guarantees systemic capital destruction.
The Model Architecture: The 4 Strategic Portfolio Quadrants
The framework evaluates each Strategic Business Unit (SBU) within a Cartesian space intersecting two structural variables: Relative Market Share ($\text{RMS}$) on the horizontal axis and Market Growth Rate ($\text{MGR}$) on the vertical axis. From this empirical intersection emerge the four canonical quadrants:
| BCG Quadrant | Relative Position ($\text{RMS}$ / $\text{MGR}$) | Cash Flow & Operating Dynamics | Gross Cash Generation vs. Reinvestment Demands | C-Level Strategic Mandate | Prototypical Business Example |
|---|---|---|---|---|---|
| ⭐ STARS | High $\text{RMS}$ ($\ge 1.0\times$) High Growth ($\ge 10\%$) |
Market leader in an expanding sector. Commands superior gross margins via scale economics, but requires heavy capital reinvestment to defend leadership. | High Generation • High Reinvestment Net Free Cash Flow ($\text{FCF}$) roughly neutral or mildly positive. |
Invest aggressively: Fund capacity scale-up, channel expansion, and R&D moats to entrench market leadership before industry maturity. | Leading enterprise SaaS platforms in hypergrowth or autonomous AI robotics divisions. |
| 🐄 CASH COWS | High $\text{RMS}$ ($\ge 1.0\times$) Low Growth ($< 10\%$) |
Scale-driven cost leader in a mature or low-growth sector. Generates massive operating cash well beyond internal reinvestment needs. | Maximum Generation • Low Reinvestment Massive structural net cash surplus ($\text{FCF} \gg 0$). |
Disciplined milking: Cap capital allocation to sustaining maintenance; systematically remit excess cash to group treasury. | Heavy hydraulic power systems, established industrial diesel engines, or legacy branded consumer staples. |
| ❓ QUESTION MARKS | Low $\text{RMS}$ ($< 1.0\times$) High Growth ($\ge 10\%$) |
Sub-scale follower in a rapidly expanding sector. Suffers operating cost penalties against the incumbent and burns cash to keep pace. | Low Generation • Massive Reinvestment Severe, chronic free cash flow deficit ($\text{FCF} \ll 0$). |
Strict binary decision: Concentrate Cash Cow surplus to cross $\text{RMS} \ge 1.0\times$ or divest/carve out immediately. | Solid-state energy storage cells competing against entrenched global battery conglomerates. |
| 🐕 DOGS | Low $\text{RMS}$ ($< 1.0\times$) Low Growth ($< 10\%$) |
Sub-scale competitor in a stagnant or contracting sector. Depressed operating margins and trapped working capital delivering sub-WACC returns. | Weak Generation • Low Reinvestment Net cash flow near zero or an active, persistent cash drain. |
Harvest or divest (M&A): Carve out to consolidating rivals, liquidate inventory, and redeploy capital into Stars. | Uninstrumented analog valves, conventional copper wiring harnesses, or obsolete peripheral hardware. |
How It Works: The Complete Strategic Planning Funnel (PESTEL → Porter → SWOT-TOWS → BCG Matrix)
For corporate leaders integrating our executive toolkits into their strategic rhythm, it is vital to recognize where the BCG Matrix sits within the end-to-end strategic planning funnel. In Tier-1 strategy consulting practice (McKinsey, BCG, Bain), strategic formulation never relies on disconnected tools; it operates as an integrated four-stage analytical funnel:
Quantitative PESTEL Matrix
Severity vs. Volatility of geopolitical, macroeconomic, and tech shocks"] M2["Stage 2: Industry Microstructure
Weighted Porter's 5 Forces
Structural industry attractiveness, rivalry, and Economic Moat defensibility"] M3["Stage 3: Internal Situational Alignment
Quantitative SWOT & TOWS Matrix
Mathematical synthesis of internal strengths/weaknesses with external factors"] M4["Stage 4: Portfolio Capital Allocation
Dynamic BCG Portfolio Matrix
Bruce Henderson liquidity equilibrium, experience curve, and CAPEX reallocation"] M1 --> M2 M2 --> M3 M3 --> M4 style M1 fill:#EFF6FF,stroke:#3B82F6,stroke-width:1.5px,color:#1E3A8A style M2 fill:#EEF2FF,stroke:#6366F1,stroke-width:1.5px,color:#312E81 style M3 fill:#ECFDF5,stroke:#10B981,stroke-width:1.5px,color:#064E3B style M4 fill:#0F172A,stroke:#D97706,stroke-width:2.5px,color:#FFFFFF
🔍 Haz clic en el diagrama para ampliarlo a pantalla completa
- Stage 1 — Exogenous Macroenvironmental Scanning (Quantitative PESTEL Matrix): The macro radar. It identifies and quantifies the P&L impact severity and temporal volatility of statutory shifts, energy price shocks, interest rate cycles, and demographic trends. If your executive team needs to audit macro risk exposure, explore our guide to the Quantitative PESTEL Matrix.
- Stage 2 — Structural Industry & Value Chain Analysis (Weighted Porter’s 5 Forces & Industry Attractiveness): Evaluates industry profitability. It examines buyer/supplier bargaining power, barriers to entry, and structural spread ($\text{ROIC} - \text{WACC}$). Learn how to quantify competitive defensibility in our guide to Weighted Porter’s 5 Forces & Industry Attractiveness.
- Stage 3 — Situational Alignment & Strategic Posture (Quantitative SWOT & TOWS Matrix): Synthesizes external risks/opportunities from PESTEL and Porter with internal organizational capabilities, defining the firm’s strategic posture and triggering actionable initiatives inside the TOWS matrix. Review this operational bridge in our guide to the Quantitative SWOT & TOWS Matrix.
- Stage 4 — Portfolio Capital Allocation & Liquidity Dynamics (Dynamic BCG Matrix): The apex of corporate finance governance. An enterprise operating across multiple business units must answer the Board’s ultimate question: where does our cash originate, and where must it be deployed to maximize long-term enterprise value? The BCG Matrix choreographs this transfer: mature Cash Cows (possessing wide Porter moats) remit surplus liquidity to fund selected Question Marks pursuing prime opportunities validated in the SWOT.
What is the Primary Objective of the BCG Matrix?
The ultimate objective of a rigorous BCG Matrix is not to produce a marketing chart, but to guarantee corporate solvency, generational business renewal, and the maximization of group Return on Invested Capital ($\text{ROIC}$). Inside the boardroom, the framework provides definitive answers to three corporate governance questions:
- Does our corporate portfolio generate sufficient internal free cash flow from mature Cash Cows to fully fund the expansion of our growth businesses without taking on dangerous levels of debt?
- Among our capital-consuming Question Marks, which single unit possesses the mathematical runway to overtake the incumbent leader ($\text{RMS} \ge 1.0\times$), and which should be carved out immediately via M&A?
- What volume of working capital and fixed assets is trapped in sub-scale Dogs generating returns below our corporate Weighted Average Cost of Capital ($\text{WACC}$)?
Expected Deliverables: What Should a Rigorous BCG Matrix Produce?
When executed under Datalaria’s quantitative consulting standard, executive leadership receives three concrete, auditable outputs:
- Dynamic Cartesian Bubble Chart ($\text{RMS}$ vs. $\text{MGR}$) Scaled by Revenue: An empirical map where each bubble represents an SBU with diameter proportional to sales volume, removing subjective bias regarding competitive positioning.
- Bruce Henderson Net Fund Balance Model ($\text{NFB}$): A treasury-level audit determining whether group cash flow is in structural surplus or running an unsustainable deficit.
- C-Level Capital Reallocation & Divestment Roadmap: A costed investment and carve-out schedule specifying CAPEX injections, M&A reserve prices, statutory C-Suite owners, quarterly Q1–Q4 milestones, and projected ROIC accretion.
2. The Fallacy of the Qualitative BCG Matrix and the Static Sketch Syndrome
When Bruce D. Henderson founded the Boston Consulting Group in 1963, he sought to address an existential corporate challenge: how should a diversified industrial holding company allocate its finite capital among disparate business lines operating across different stages of maturity?
In a series of landmark essays published in the BCG Perspectives, Henderson introduced the Growth-Share Matrix. However, decades of academic oversimplification have generated three widespread corporate distortions:
2.1. The Absolute Share Distortion
In management meetings, one frequently hears: “Our industrial robotics division is a market leader because we have captured 22% of the domestic market”. If the sector is highly fragmented and the runner-up holds 8%, the company does indeed enjoy a scale advantage ($\text{RMS} = 2.75\times$). But if the industry is dominated by a global player holding 66%, the division is in reality a marginal operator ($\text{RMS} = 0.33\times$).
Enterprise profitability and cash generation do not stem from abstract market percentages, but from scale advantage relative to the primary competitor. As Henderson proved, manufacturing costs decline with accumulated internal experience relative to the dominant rival, not with total industry volume.
2.2. The Question Mark Capital Dilution Trap
Without a dynamic cash model, corporations default to “budgetary egalitarianism”: granting uniform percentage CAPEX increases (e.g. +5% annually) across all business units. Units classified as Question Marks operate in high-growth markets but suffer from low relative market share. These businesses are cash sinks: they demand immense capital to fund capacity, sales pipelines, and working capital, yet generate minimal cash flow due to sub-scale margins.
Spreading capital thinly across four or five Question Marks simultaneously guarantees that none of them achieves the scale required to surpass the market leader ($\text{RMS} \ge 1.0\times$). When market growth inevitably moderates, the company finds itself burdened with a portfolio of new Dogs.
2.3. The Executive “Last-Mile” Decision Gap
A strategy session that concludes with an illustrated slide without linking to corporate cash flow, debt covenants, and Return on Invested Capital ($\text{ROIC}$) fails the Board of Directors. Executive leadership requires concrete answers to three questions:
- Exactly how much net surplus cash in euros/dollars must Cash Cows remit to corporate treasury during the upcoming fiscal year?
- Which Question Mark possesses the mathematical runway to cross the $\text{RMS} \ge 1.0\times$ threshold under an aggressive, concentrated capital injection?
- Which trapped working capital and fixed assets in Dogs must be liquidated before Q3 to protect the firm’s balance sheet?
3. Mathematical Foundations: Portfolio Dynamics, Relative Share & The Experience Curve
To establish an auditable analytical framework (McKinsey / BCG Tier-1 standard), each Strategic Business Unit (SBU) is defined as a two-dimensional mathematical vector within Cartesian coordinates:
🔍 Haz clic en el diagrama para ampliarlo a pantalla completa
3.1. Relative Market Share ($\text{RMS}_i$) Equation
Relative Market Share governs the horizontal axis. It benchmarks the evaluated SBU directly against the largest operator in that market segment:
$$\text{RMS}_i = \frac{V_i}{V_{\text{leader}, i}}$$Where:
- $V_i$: Annual revenue or sales volume of evaluated SBU $i$.
- $V_{\text{leader}, i}$: Annual revenue of the leading competitor in that specific market segment.
- Inversion Rule for Market Leaders: If the evaluated SBU is the undisputed number one player in the segment, its relative share is calculated against the second-largest competitor ($\text{RMS}_i = V_i / V_{\text{runner-up}, i}$). Under this condition, $\text{RMS}$ is strictly greater than $1.00\times$.
The Canonical Cutoff Threshold: Positioned universally at $\text{RMS}_{\text{cutoff}} = 1.00\times$. An $\text{RMS} \ge 1.00\times$ establishes market leadership and lowest unit cost. An $\text{RMS} < 1.00\times$ places the business unit in a structural scale deficit.
3.2. Market Growth Rate ($\text{MGR}_i$) Equation
The vertical axis measures the annualized expansion velocity of total transaction volume in the relevant sector:
$$\text{MGR}_i = \left( \frac{M_{i, t} - M_{i, t-1}}{M_{i, t-1}} \right) \times 100\%$$Where $M_{i, t}$ denotes total market size in year $t$.
The Canonical Cutoff Threshold: Set conventionally at $\text{MGR}_{\text{cutoff}} = 10.0\%$ annually (or the nominal GDP growth rate plus sector inflation). A rate $\ge 10.0\%$ characterizes an expanding market that demands heavy capital reinvestment. A rate $< 10.0\%$ denotes a mature or stagnant market with low capital reinvestment intensity.
3.3. Bruce Henderson’s Experience Curve Power Law
The economic link connecting Relative Market Share to operating profitability is the Experience Curve formulated by BCG in 1968:
$$C_n = C_1 \cdot n^{-b}$$Where:
- $C_n$: Real value-added unit cost after producing cumulative unit $n$.
- $C_1$: Direct unit cost of the first unit produced.
- $n$: Cumulative total production volume over the enterprise’s operating history.
- $b$: Learning elasticity exponent ($b > 0$).
The parameter $b$ is derived from the Progress Ratio ($\text{PR}$) of the industry (typically between 70% and 80% in advanced manufacturing, precision engineering, and SaaS platforms):
$$b = -\frac{\ln(\text{PR})}{\ln(2)}$$For an 80% progress ratio ($\text{PR} = 0.80$), $b = -\ln(0.80)/\ln(2) \approx 0.322$. This mathematical proof dictates that each time cumulative production doubles, unit costs fall by 20% in real terms.
Because the SBU with the highest Relative Market Share ($\text{RMS} \ge 1.0\times$) accumulates production volume faster than its peers, it descends the cost curve ahead of the competition. Consequently, the market leader enjoys structural, compounding advantages in gross margin and EBITDA generation.
3.4. Net Free Cash Flow ($\text{FCF}$) Equation
The net cash balance of each quadrant is dictated by standard discounted cash flow dynamics:
$$\text{FCF}_i = \text{EBITDA}_i \cdot (1 - t) - \Delta \text{NWC}_i - \text{CAPEX}_{\text{maintenance}, i} - \text{CAPEX}_{\text{growth}, i}$$- In high-growth sectors ($\text{MGR} \ge 10\%$), growth CAPEX ($\text{CAPEX}_{\text{growth}}$) and working capital investment ($\Delta \text{NWC}$) absorb vast cash reserves to build manufacturing lines and inventory.
- In low-growth sectors ($\text{MGR} < 10\%$), growth CAPEX approaches zero ($\text{CAPEX}_{\text{growth}} \approx 0$), and working capital needs stabilize.
4. Bruce Henderson’s Golden Rules of Capital Allocation
Henderson’s central insight was that the four quadrants represent phases within an integrated corporate cash lifecycle governed by internal capital transfers:
| BCG Quadrant | Relative Share ($\text{RMS}$) | Market Growth ($\text{MGR}$) | Gross Cash Generation | Reinvestment Needs | Net Free Cash Flow ($\text{FCF}$) | C-Level Strategic Mandate |
|---|---|---|---|---|---|---|
| ⭐ STARS | High ($\ge 1.0\times$) | High ($\ge 10\%$) | High (scale-driven gross margins) | Very High (defending market share) | Near zero or mild positive | Aggressive investment: Reinvest all generated cash to secure manufacturing and technology moats until market maturity. |
| 🐄 CASH COWS | High ($\ge 1.0\times$) | Low ($< 10\%$) | Maximum (lowest unit costs in mature sector) | Minimal (sustaining CAPEX only) | Massive cash surplus (+) | Disciplined milking: Strictly cap expansion CAPEX; remit surplus liquidity to corporate treasury. |
| ❓ QUESTION MARKS | Low ($< 1.0\times$) | High ($\ge 10\%$) | Weak (depressed margins from scale deficit) | Very High (rapidly expanding market) | Severe cash deficit (-) | Binary decision: Inject massive Cash Cow funds to capture #1 ($\text{RMS} \ge 1.0\times$) or divest immediately. |
| 🐕 DOGS | Low ($< 1.0\times$) | Low ($< 10\%$) | Weak or negative | Low or moderate | Neutral or chronic cash drain (-) | Harvest or M&A carve-out: Divest assets to consolidating rivals and redeploy capital into Stars. |
4.1. The Virtuous Portfolio Lifecycle
A strategically healthy corporation functions as a self-sustaining financial ecosystem:
- Cash Cows fund the future: Generating recurrent cash surpluses that cannot be profitably reinvested in mature sectors without creating industry overcapacity.
- Selective concentration on Question Marks: Cash Cow surpluses are directed exclusively into one or two high-potential Question Marks to fund the capacity expansion or IP acquisitions required to surpass the incumbent leader.
- Ascension to Stars: Once the Question Mark crosses the $\text{RMS} \ge 1.00\times$ threshold, it becomes a self-funding Star.
- Maturation into Cash Cows: As the industry growth rate moderates below 10%, the Star naturally transitions into a Cash Cow, safeguarding corporate dividends for the subsequent decade.
4.2. Henderson’s Four Fatal Portfolio Traps
Bruce Henderson identified four recurring executive capital allocation errors:
- Trap 1: Overmilking Cash Cows: Starving mature cash engines of essential maintenance CAPEX. Customer retention erodes, secondary competitors capture share, and the unit falls below $\text{RMS} = 1.0\times$, prematurely degrading into a Dog and destroying the group’s dividend engine.
- Trap 2: Feeding the Dogs: Yielding to internal corporate politics or legacy sentimental attachments by funding turnaround programs in sub-scale businesses facing stagnant demand. Every euro sunk into a Dog is capital withheld from scaling a Star.
- Trap 3: Scattering Question Marks: Thinly distributing investment capital across four or five ventures simultaneously. None of them achieves the scale necessary to overtake the incumbent leader, the market matures, and the firm ends up with a portfolio of new Dogs.
- Trap 4: Portfolio Aging: Maintaining a portfolio composed entirely of mature Cash Cows and Dogs. While current cash flows appear robust, the company possesses no pipeline of future Stars to replace mature lines when secular obsolescence arrives.
5. The Cartesian Portfolio Matrix and Corporate Cash Flow Balance
To audit group strategic resilience, the Datalaria framework assesses Bruce Henderson’s Net Fund Balance ($\text{NFB}$):
$$\text{NFB} = \sum \text{FCF}_{\text{Cows}} + \sum \text{FCF}_{\text{Stars}} - \sum |\text{FCF}_{\text{Questions}}| - \sum |\text{FCF}_{\text{Deficit Dogs}}|$$- When $\text{NFB} > 0$ (Structural Surplus): The portfolio is self-funding and generates discretionary cash for shareholder dividends, debt deleveraging, or accretive strategic M&A.
- When $\text{NFB} < 0$ (Structural Deficit): The portfolio consumes more liquidity than it generates. The enterprise must rely on external debt or equity dilution to support growth, elevating corporate insolvency risk during periods of credit tightening.
6. Solved Industrial B2B Case Study: Nexus Industrial Technologies Group
To demonstrate execution before an executive Board of Directors, we examine the anonymized corporate portfolio of Nexus Group, an international industrial technology conglomerate.
6.1. Operational and Financial Baseline
- Consolidated Annual Revenue: €107.0M
- Consolidated EBITDA: €18.98M (Consolidated EBITDA margin: 17.7%)
- Net Free Cash Flow ($\text{FCF}$): +€5.29M
- Operating Structure: 8 Strategic Business Units (SBUs) spanning industrial automation, IoT SaaS, heavy machinery, energy storage, and legacy hardware.
6.2. Quantitative Audit of the 8 SBUs (Datalaria Model)
| SBU ID | Strategic Business Unit Name | Own Sales ($V_i$) | Leader Sales ($V_{\text{leader}}$) | Relative Share ($\text{RMS}$) | Market Growth ($\text{MGR}$) | EBITDA Margin | EBITDA Generated | Net Annual FCF | Assigned BCG Quadrant |
|---|---|---|---|---|---|---|---|---|---|
| SBU-01 | Autonomous AI Vision Robotics | €18.5M | €14.8M | 1.25x | +18.5% | 22.0% | €4.07M | +€0.65M | ⭐ STAR |
| SBU-02 | Industrial IoT SaaS Platform | €12.2M | €10.5M | 1.16x | +24.0% | 25.0% | €3.05M | +€0.28M | ⭐ STAR |
| SBU-03 | Heavy Hydraulic Power Systems | €32.0M | €16.0M | 2.00x | +3.5% | 20.0% | €6.40M | +€4.85M | 🐄 CASH COW |
| SBU-04 | Industrial Combustion Engines | €24.5M | €17.5M | 1.40x | +2.0% | 18.0% | €4.41M | +€3.20M | 🐄 CASH COW |
| SBU-05 | Solid-State Batteries & Storage | €6.5M | €18.5M | 0.35x | +32.0% | 6.0% | €0.39M | -€2.15M | ❓ QUESTION MARK |
| SBU-06 | Quantum Laser Sensing Systems | €3.8M | €15.2M | 0.25x | +21.0% | 4.0% | €0.15M | -€1.45M | ❓ QUESTION MARK |
| SBU-07 | Conventional Copper Wiring | €5.2M | €20.8M | 0.25x | +1.0% | 5.0% | €0.26M | -€0.18M | 🐕 DOG |
| SBU-08 | Analog Pneumatic Valves | €4.3M | €14.3M | 0.30x | -1.5% | 7.0% | €0.30M | +€0.09M | 🐕 DOG |
| TOTAL | PORTFOLIO CONSOLIDATED | €107.0M | - | 1.09x | +8.2% | 17.7% | €18.98M | +€5.29M | SUSTAINABLE |
6.3. Financial Diagnosis and Henderson Balance
The empirical model revealed a strategic profile characteristic of established manufacturing holdings:
- Elevated Cash Cow Dependency: 52.8% of group revenue (€56.5M) and 75% of EBITDA are concentrated in two mature divisions (Hydraulics and Engines) expanding at under 3.5% annually. Without proactive portfolio renewal, group cash flows will contract by 35% over the next 7 years.
- Healthy Net Fund Surplus: The two Cash Cows produce +€8.05M in net annual FCF, comfortably absorbing the combined expansion deficits of the two Question Marks (-€3.60M), leaving a net group surplus of +€4.45M.
- Hidden Economic Drag in Dogs: The two Dog units lock up €9.5M in sales and over €2.8M in working capital, consuming executive bandwidth while delivering an average ROIC of 4.2% against a corporate WACC of 8.5%.
6.4. Boardroom Capital Allocation Roadmap Approved
Guided by this quantitative audit, the Board of Directors of Nexus Group ratified a Four-Pillar Capital Reallocation Plan for 2026:
- Pillar 1: Concentrated Push in Solid-State Batteries (SBU-05 - €2.8M CAPEX): Reallocating €2,800,000 from the Hydraulics cash surplus to expand automated cell assembly, scaling $\text{RMS}$ from $0.35\times$ to $1.05\times$ over an 18-month horizon to establish a new Star.
- Pillar 2: Strategic Joint Venture for Quantum Laser (SBU-06): Recognizing that group treasury cannot fund two capital-intensive pushes simultaneously, the Chief Business Officer (CBO) is authorized to negotiate a 50% co-investment partnership with an international optical conglomerate, eliminating the €1.45M annual cash drain.
- Pillar 3: M&A Carve-Out Sale for Copper Wiring (SBU-07 - €3.2M Proceeds): Granting an exclusive M&A sale mandate to divest plant machinery, contracts, and inventory to a regional competitor at a firm floor price of €3.2M in clean cash.
- Pillar 4: Phased Harvest and Sunset of Analog Valves (SBU-08): Orderly inventory liquidation during Q3 and redeployment of 14 mechatronics engineers into the AI Robotics division (SBU-01).
Projected Financial Accretion: Corporate ROIC improves from 16.0% to 19.2% (+320 basis points), projected annual EBITDA expands by €4.45M upon transition completion, and the capital investment program achieves payback within 18.2 months.
7. Official Executive Decision Pack: Dynamic BCG Portfolio Matrix
For Chief Executive Officers (CEOs), Chief Financial Officers (CFOs), Heads of Corporate Strategy, and Partners in private equity and advisory firms requiring an enterprise-grade toolkit (McKinsey / BCG standard), we have assembled the complete programmatic pack:
Executive Decision Pack: Dynamic BCG Portfolio Matrix & Capital Allocation
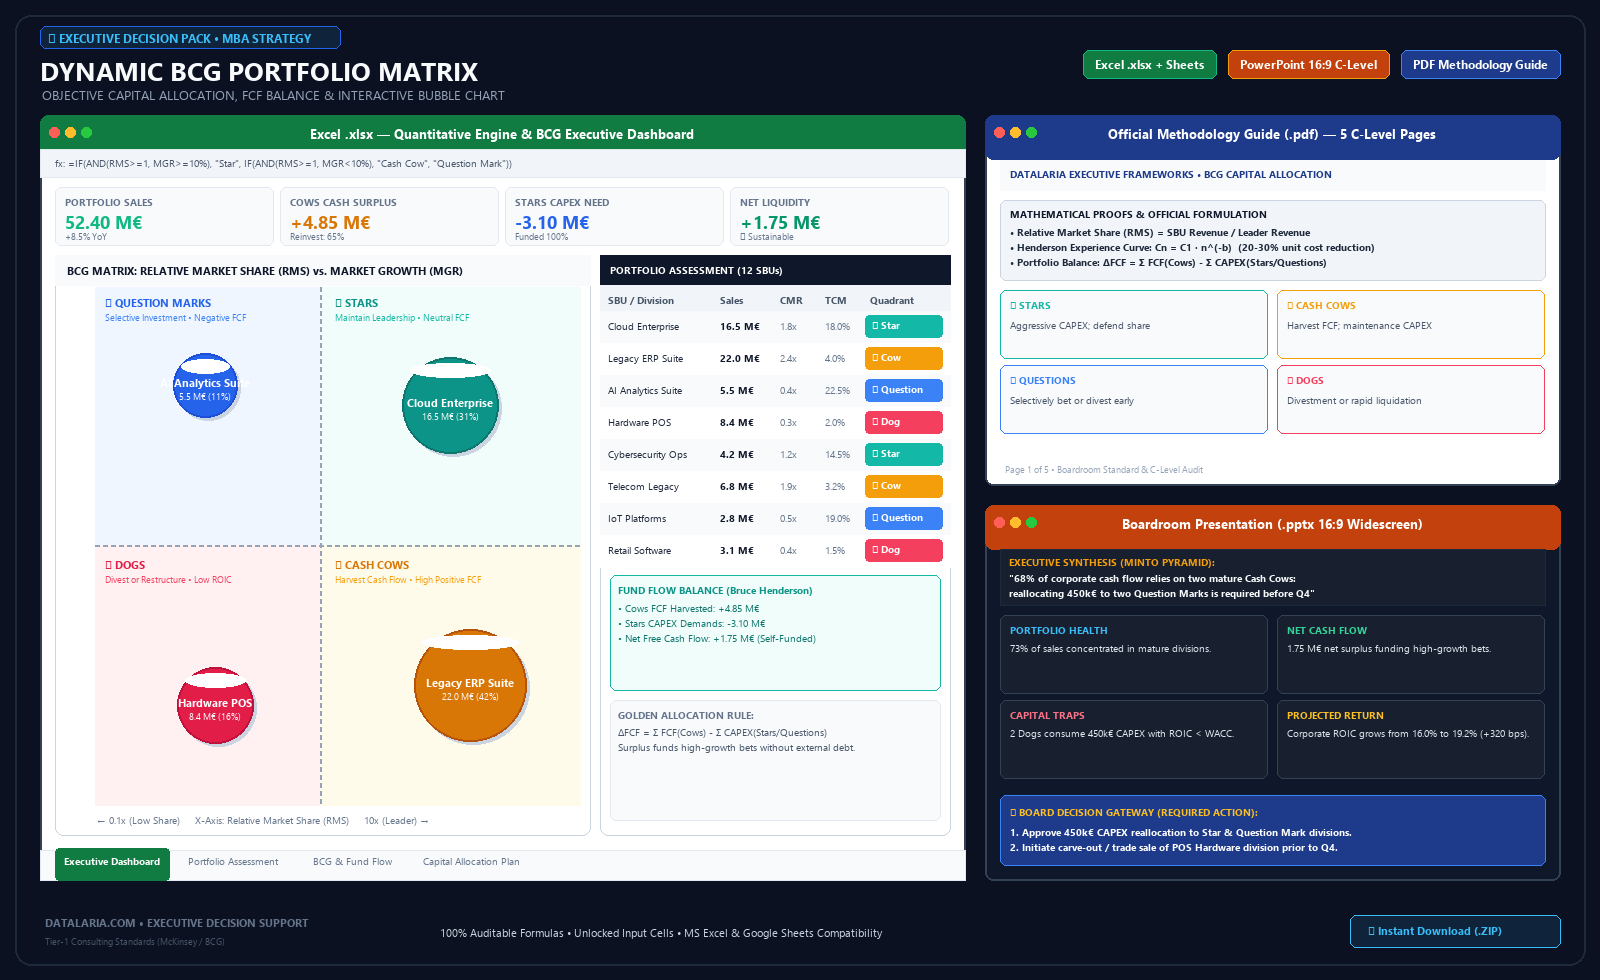 🔍 Actual preview of included deliverables: Quantitative Excel Engine (.xlsx) with Dynamic Bubble Chart and Henderson Cash Balance, 16:9 C-Level Presentation (.pptx), and 5-page PDF Methodology Guide. (Click to enlarge)
- Quantitative Excel model (.xlsx) with 4 interconnected tabs, protected matrix formulas, and dynamic bubble chart auto-scaled by division revenue
- Automated Relative Market Share (RMS) and Market Growth Rate (MGR) calculations with 4-quadrant categorization
- Editable PowerPoint presentation (.pptx 16:9 Widescreen) structured under the Minto Pyramid, Action Titles, and Board Decision Gateway
- Official 5-page PDF Methodology Guide with Henderson mathematical proofs, reinvestment rules, and Boardroom FAQ
- Guaranteed 100% compatibility with Microsoft Excel and Google Sheets without macro dependencies
8. Boardroom Defense Protocol (C-Level FAQ)
Why divest a Dog that still produces positive accounting EBITDA?
Because positive accounting profit often masks economic value destruction. When a business unit generates €90,000 in EBITDA on €2,500,000 in operating assets, its Return on Invested Capital ($\text{ROIC}$) is approximately 3.6%. If the corporate Weighted Average Cost of Capital ($\text{WACC}$) is 8.5%, the unit destroys €122,500 in economic value every single year. Divesting those assets for €3.2M and reinvesting the proceeds into a Star generating a 22% ROIC creates immediate shareholder wealth.
How do we select which Question Mark deserves Cash Cow funding?
By applying three sequential quantitative hurdles:
- Scale Runway to $\text{RMS} \ge 1.0\times$: Demonstrable probability of surpassing the incumbent’s cumulative volume before industry growth moderates.
- Capital Intensity: The total CAPEX required to double market share relative to the available Cash Cow cash surplus.
- Growth Runway Durability: High confidence that market expansion ($\text{MGR}$) will remain above 10% for at least 4 additional years, enabling capital recovery. Any venture failing these tests must be carved out or shared via Joint Venture.
How do we keep the executive management of Cash Cow divisions motivated?
By decoupling management bonuses from revenue growth targets (an inappropriate metric for mature markets) and anchoring incentives 100% on net Free Cash Flow ($\text{FCF}$) generation, lean working capital management ($\text{NWC}$), and market share preservation. Cash Cow leaders must be recognized at the Board level as the primary guarantors of corporate dividends and expansion funding.
How should the Board manage cannibalization risk between Stars and Question Marks?
Bruce Henderson formulated an unambiguous rule: if an emerging technology is destined to disrupt an established cash engine, it is vastly preferable for the company to cannibalize itself internally before an external competitor captures the entire market. The optimal corporate response is to accelerate internal adoption by transferring key engineering talent to the new line.
9. Authoritative Canonical Bibliography
-
Henderson, Bruce D. (1970). The Product Portfolio. Boston Consulting Group Perspectives, No. 66, Boston.
Foundational treatise introducing the growth-share matrix and establishing the economic principles governing internal cash flow equilibrium. View original perspective at bcg.com -
Henderson, Bruce D. (1968). The Experience Curve. Boston Consulting Group, Boston.
The seminal empirical study on real unit cost reductions driven by cumulative volume doubling, providing the theoretical basis for relative market share advantages. ISBN:978-0878460656 -
Day, George S. (1977). “Diagnosing the Product Portfolio”. Journal of Marketing, Vol. 41, No. 2, pp. 29-38.
Canonical academic study analyzing capital misallocation hazards and structural portfolio aging in diversified corporations. DOI:10.1177/002224297704100206 -
Porter, Michael E. (1980). Competitive Strategy: Techniques for Analyzing Industries and Competitors. Free Press, New York.
Foundational work integrating scale-driven cost leadership, industry entry barriers, and strategic competitive positioning. ISBN:978-0684841489 -
Minto, Barbara (2009). The Pyramid Principle: Logic in Writing and Thinking. Financial Times / Prentice Hall (3rd Edition).
The gold standard in executive communication, deductive reasoning, and Action Titles utilized across Tier-1 strategy consulting firms. ISBN:978-0273710516 -
McKinsey & Company, Koller, T., Goedhart, M., & Wessels, D. (2012). Valuation: Measuring and Managing the Value of Companies. John Wiley & Sons, New York (5th Edition).
The definitive corporate finance reference linking Return on Invested Capital ($\text{ROIC}$), organic revenue growth, and shareholder value creation. ISBN:978-0470427774